
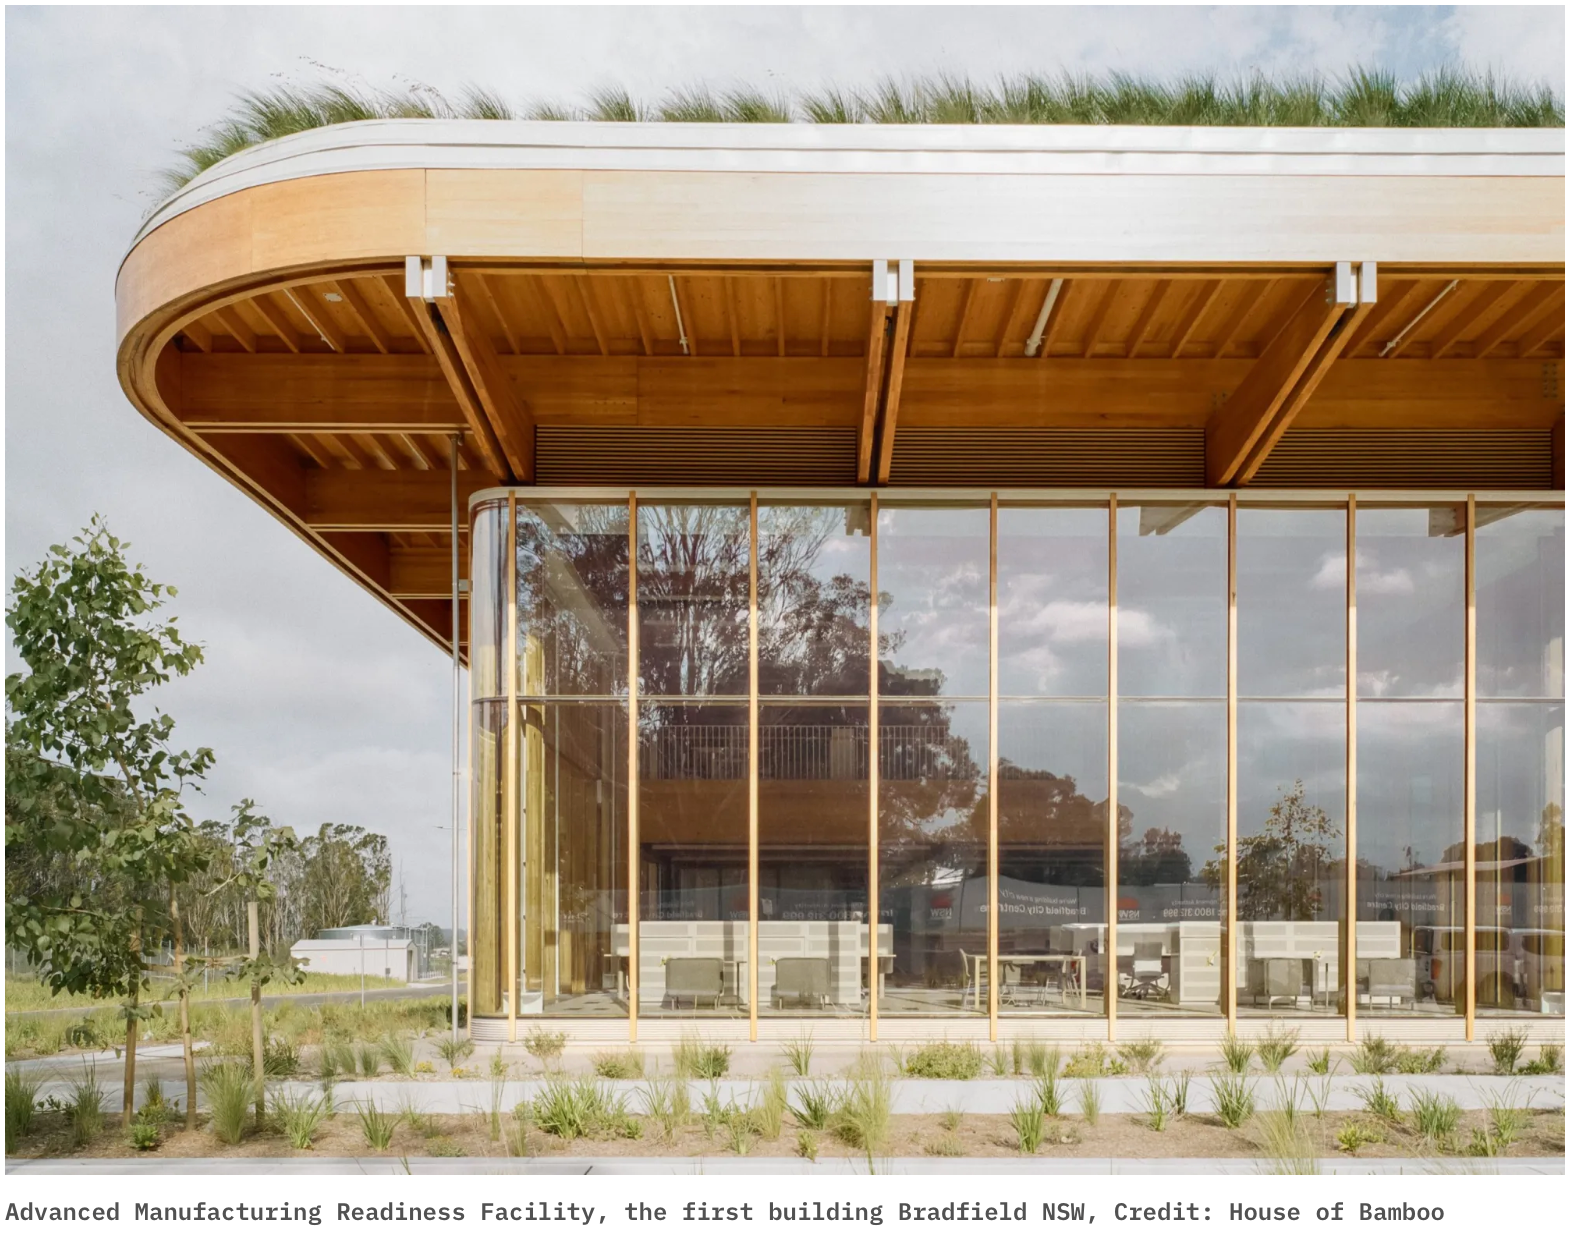
By Jeremy Mansfield, 29 September 2026 Published on TheFifthEstate Australia has set itself two difficult tasks: build vastly more homes and cut the upfront carbon locked into the materials we use to build them. New analysis from Deloitte Access Economics suggests an Australian engineered bamboo industry could make a measurable contribution to both. By 2035, under the report’s high-growth scenario, Australia could produce enough engineered bamboo for the equivalent of around 16,600 homes a year and avoid around 430,000 tonnes of greenhouse gas emissions in that year, about 1.5 per cent of the built environment’s upfront embodied carbon. The report also estimates the construction sector could gain an average $111 million in additional value each year. So, what stands between that 1.5 per cent opportunity and the buildings we actually build? The gap between crop and construction Last January in The Fifth Estate , I wrote that Australia’s net zero settings still default to slow plantation cycles, and that public finance has no real home for fast-growing biobased materials. The Bamboo Breakthrough roadmap and the analysis now give investors something firmer to look at. A local engineered bamboo industry could be an $847 million a year market by 2035 under a high growth scenario. This would add about $906 million to GDP and support around 1840 jobs. About three-quarters of those jobs are in manufacturing. The material volume under the scenario is equivalent to about 250,000 cubic metres a year. However, Australia currently has no coordinated commercial plantation base. No domestic manufacturer of structural engineered bamboo. No deemed-to-satisfy path in the National Construction Code. Performance solutions can carry early projects, as they have done for mass engineered timber. Policy and funding frameworks were written around incumbent materials. Harvesting and manufacturing must move with the crop. One without the other does not work. Building the evidence base The first four years in the report’s pathway are about proving the product and taking risk out of delivery. That is now, not 2035. The first project is not a national hectare target. It is a pilot plantation with a named offtake, processing designed against that offtake, and Australian performance data so a certifier can say yes. Demonstration buildings using proven international products are part of that. They build demand and performance data while local plantations mature. It will take time to build the sovereign manufacturing capability and reliable supply chain to turn a crop into a construction product. The roadmap also identifies research needed to reduce risk, from farm-ready harvest methods to a carbon method that can account for selective harvest. A bamboo forest method idea has sat with the Department of Climate Change, Energy, the Environment and Water since June 2024, waiting for support to take it to an expression of interest. Soil carbon is a separate question. Baselines and how selective harvest that leaves the root system in the ground should be treated still have to be worked through with the Clean Energy Regulator. Beyond the bamboo beam There are also research opportunities for other use cases. The report’s high growth case is not only about laminated lumber replacing glulam. A large share of the modelled abatement is engineered bamboo in place of medium density fibreboard (MDF) and other building products, with smaller plays in aluminium and steel. Fibre, panels, cladding, flooring and interior uses are part of that market. Combinations of bamboo fibres with other fast growing fibres already in Australian agriculture have not been taken far yet. That research is how more of the modelled industry becomes a product with a buyer. There is also a hybrid opportunity with timber. Engineered bamboo can sit in mixed systems, not only as a standalone product. That is useful where mills already handle wood fibre and want another feedstock, and where specifiers want a family of biobased materials rather than a single substitute. Recognising engineered bamboo in industry carbon tools is a separate task. Environmental product declarations (EPDs) exist, but NABERS embodied carbon does not yet include a category for engineered bamboo, and neither does EC3 or many other lifecycle assessment tools. That gap can be fixed, but it will not close automatically. The Clean Energy Finance Corporation (CEFC), the National Reconstruction Fund, Northern Australia Infrastructure Facility (NAIF), the Regional Investment Corporation and Housing Australia all sit close to housing supply, regional manufacturing, agriculture or embodied carbon. The question is whether a perennial grass that becomes an engineered beam can be recognised as a fit, rather than forced into a forestry or energy template that does not describe it. The investment case is there for anyone prepared to look at crop and processing together. That is the work from here, in 2026. Download the Bamboo Breakthrough roadmap .
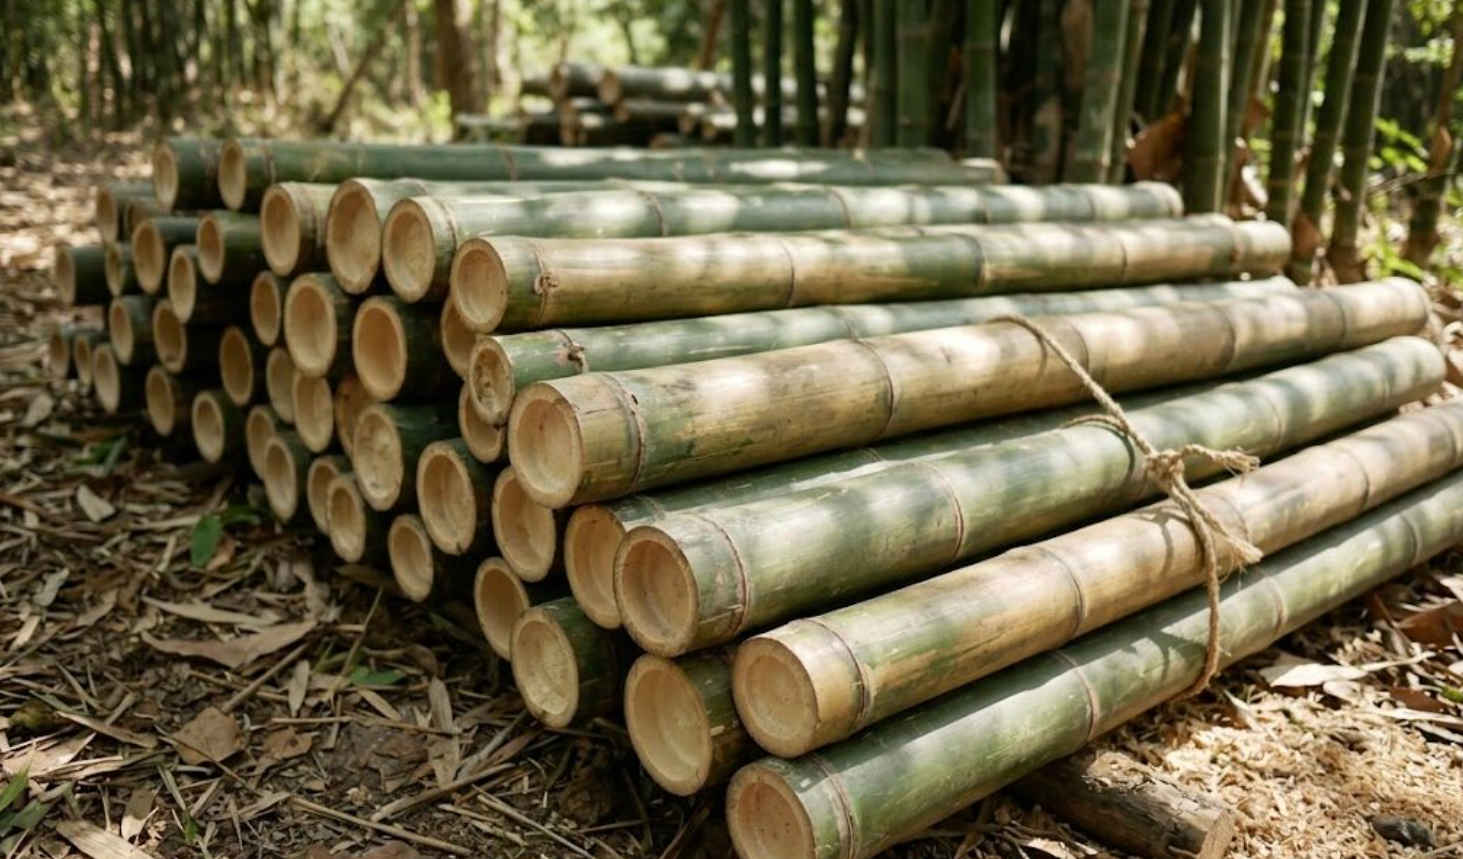
Created by Jeremy Mansfield First published on Sourceable here Not many people have realised we have moved on from tiki-bar bamboo poles. Engineered bamboo is now a construction product. It can be used in mainstream building, not just furniture, screens and holiday-deck aesthetics.
Why Speed Matters: The Time Value of Carbon in Decarbonisation
Persistent Blind Spots: Refrigerants Are Still Hiding in Plain Sight – 2026 Update
Commissioning: It’s in Your A5 Footprint – Here’s Why It Matters
Could Australia Become a Dumping Ground for Refrigerants? (May 2026 Update)
Construction Emissions Intensity: The Case for Operational Control A5 Boundary Reporting Over Financial Control
Why Australia’s net zero plan needs fast-growing biobased partners
Beyond Greenwashing: Protecting Fair Competition and Ethical Supply Chains in the Transition to Net-Zero
Why Energy Efficiency Must Be Central to Decarbonising Diesel-Dependent Equipment Sectors
Timber Needs Its Biobased Bedfellows: Why the Fastest Path to Decarbonising Construction is a Family Affair
Unseen and Unaccounted For: Closing the Refrigerant Gap in Decarbonisation / Net Zero Strategies
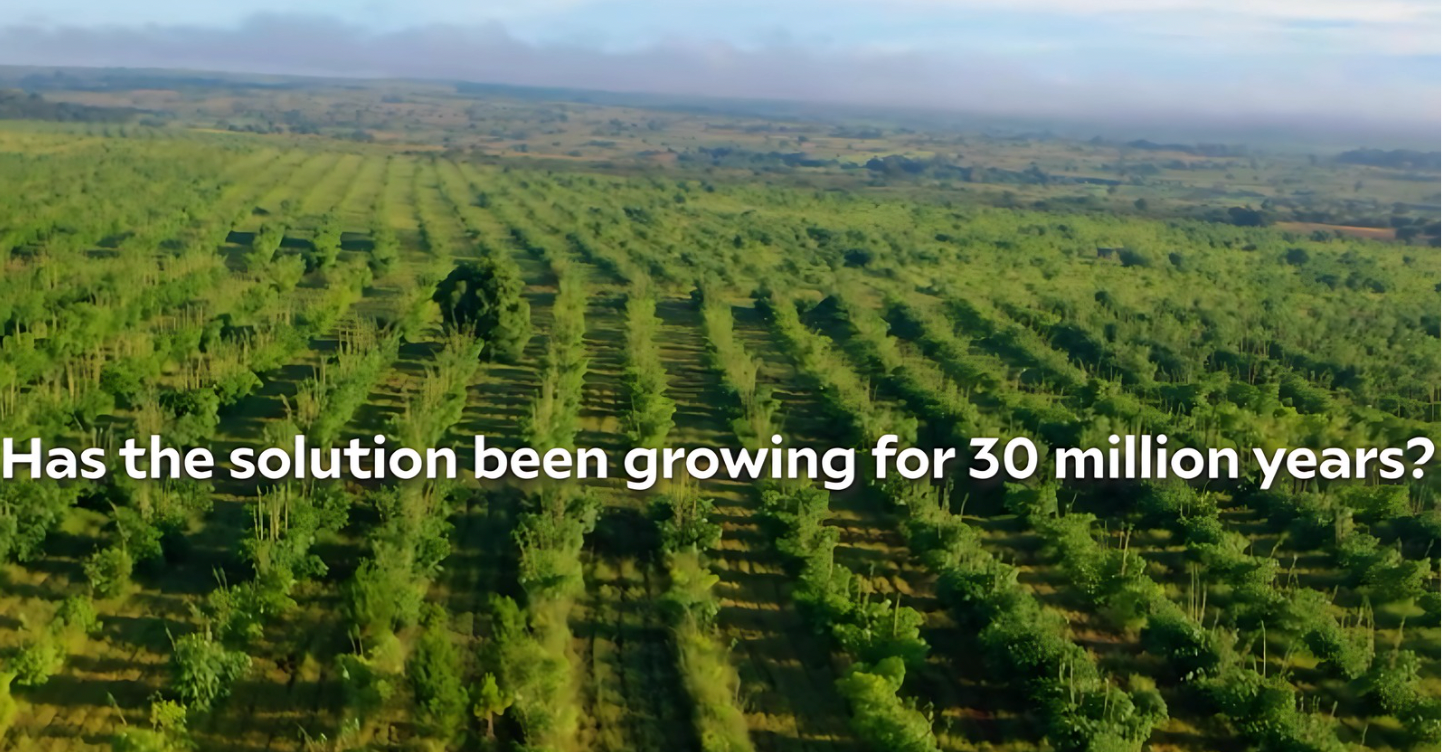
Bamboo: Unlocking Climate Solutions with Australia’s Sustainable Finance Taxonomy
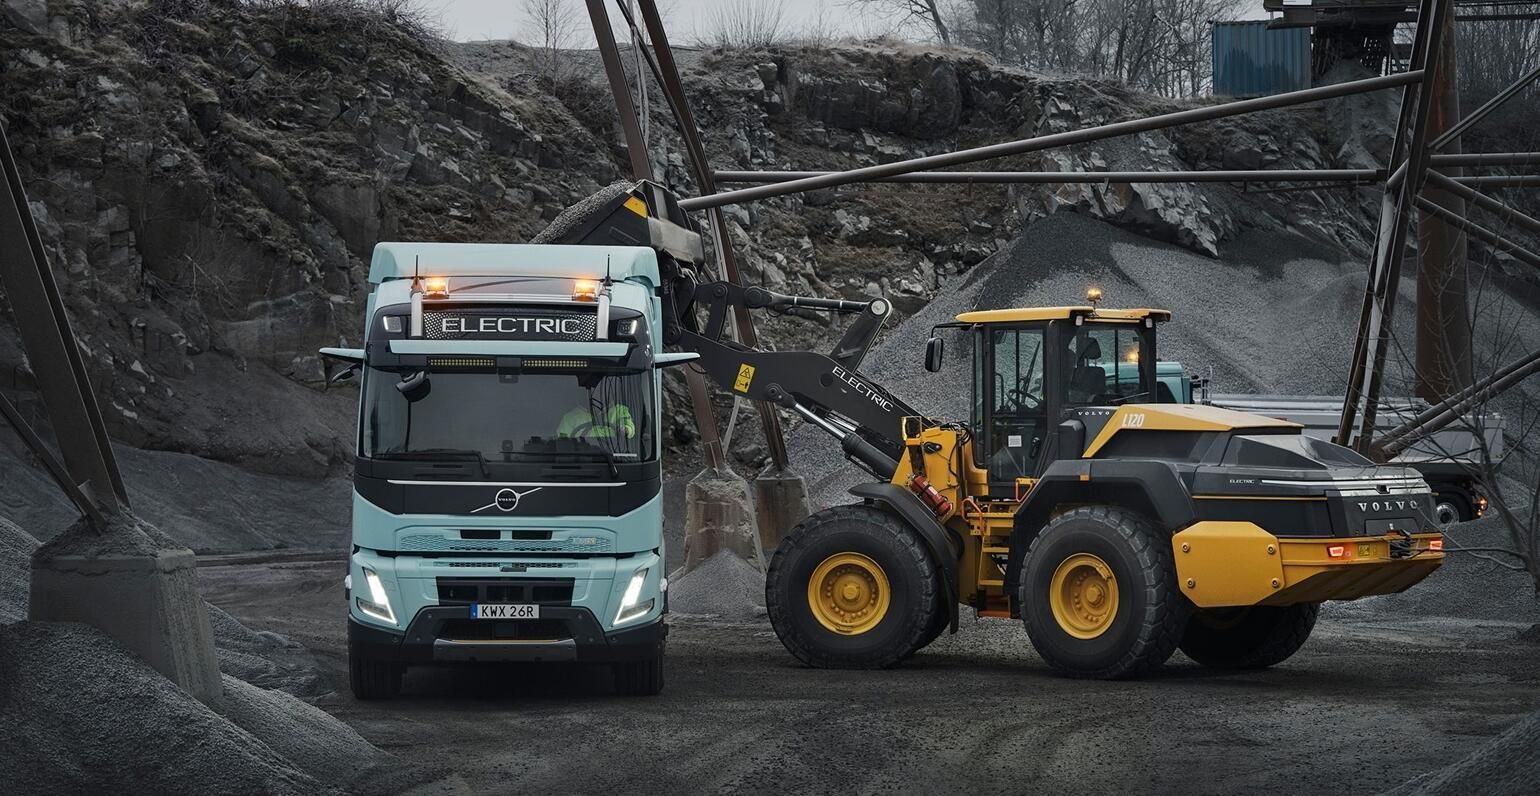
Accelerating the Transition to Fossil Fuel-Free Construction Mansfield Advisory Pty Ltd 205 followers May 27, 2025 By Jeremy Mansfield OAM , Mansfield Advisory Pty Ltd Introduction The construction industry accounts for 40% of global carbon emissions, with a significant portion stemming from onsite activities and embodied carbon in materials [1]. In Australia, where infrastructure and buildings are key economic drivers, the sector’s emissions—particularly from construction processes (A5 emissions)—present both a challenge and an opportunity. Fossil fuel-free construction, which eliminates fossil fuels from onsite energy, machinery, transportation, and materials, is a critical step toward net zero by 2050. At Mansfield Advisory, we are committed to driving this transformation. Drawing on insights from ASBEC’s Our Upfront Opportunity report [1], Infrastructure Australia’s Embodied Carbon Projections for Australian Infrastructure and Buildings [2], the NABERS Embodied Carbon framework [3], and the C40 Clean Construction Accelerator, this article outlines the path to fossil fuel-free construction. It’s a call to action for government and industry to collaborate on policies and practices that will reshape how we build. What is Fossil Fuel-Free Construction? Fossil fuel-free construction eliminates fossil fuels across onsite activities (A5 emissions under EN15978), focusing on four key areas: Energy Sources : Powering construction sites with onsite or offsite renewable energy like solar, wind, or hydropower. Machinery : Using renewable electricity, low-carbon liquid fuels or renewable hydrogen to power machinery and equipment, instead of diesel, LPG or gasoline. Transportation : Deploying electric or low-carbon liquid fuel vehicles for moving materials and workers. Materials : Prioritising low-carbon options that minimise fossil fuel use in production.
Could Australia Become A Dumping Ground for Refrigerants?